Should Your Teenager Have a Debit Card? Pros, Cons, and Ground Rules
For most teens, yes, with limits, parental visibility, and regular check ins. A debit card lets teens practice managing real money while mistakes are still small.
Read ArticlePlain-English guides on investing, personal finance, and market fundamentals — for every experience level.
Featured

For most teens, yes, with limits, parental visibility, and regular check ins. A debit card lets teens practice managing real money while mistakes are still small.
Read Article
For most teens, yes, with limits, parental visibility, and regular check ins. A debit card lets teens practice managing real money while mistakes are still small.

Talk early, talk often, and use real life moments. Short, repeated conversations about paychecks, budgeting, credit, debt, saving, and online safety prepare teens better than one big talk.

The best free programs are practical, relevant to students' real lives, hands on, and connected to a next step like a savings account or ongoing support. Free curriculum is easy to find. Making it stick takes thoughtful delivery and follow through.

Students arrive in personal finance classes with very different backgrounds. Adaptive learning adjusts pacing, practice, and difficulty to each student, so those who fall behind get extra support while others keep moving. It works best alongside a teacher, not instead of one.

Teach time, diversification, and habits, not stock picking. Teenagers have one huge advantage over every other investor: decades of time. Lessons that reward patience and consistency teach more than a contest that rewards a lucky pick.

Every North Carolina public high school student must pass a full year Economics and Personal Finance (EPF) course to graduate, starting with students who entered ninth grade in the 2020 to 2021 school year (the Class of 2024). Teachers have strong free resources and a state supported training path to help them teach it well.

The credit union mission is already about improving members' financial lives. A structured financial wellness program makes that mission visible, measurable, and competitive. Members who feel their credit union helped them get ahead stay longer and use more services.

Credit unions can turn young members into lifelong owners by pairing accounts that grow with the child with education that builds confidence. The cooperative model gives you a story banks can't tell: members own the institution that's teaching them.

Start small, listen first, and stay consistent. The school partnerships that last solve a problem teachers already have. In North Carolina, that problem is clear: every high school student must pass a full year Economics and Personal Finance course, and teachers welcome help that fits it.

Your branch staff handle real money decisions every day, live in the community, and are trusted locally. That makes them more credible teachers than outside presenters. Their involvement also matters for CRA, since community development services generally require bank employees to provide them.

Examiners want proof of four things: what you did, who you served, how your employees were involved, and what it achieved. Most importantly, they want evidence the program was targeted to low and moderate income (LMI) people. Good programs lose credit every year because the paperwork doesn't show it.

Pair financial education with real, low cost youth accounts. Education builds trust and confidence, the account turns that trust into a relationship, and a relationship that starts at 15 can last 50 years. Treat it as a long term deposit pipeline, not a one time community event.

Lead with the business opportunity, show evidence that education works, propose a small pilot with clear metrics, and close with a specific ask and review date. Boards fund clarity and limited risk, not good intentions.

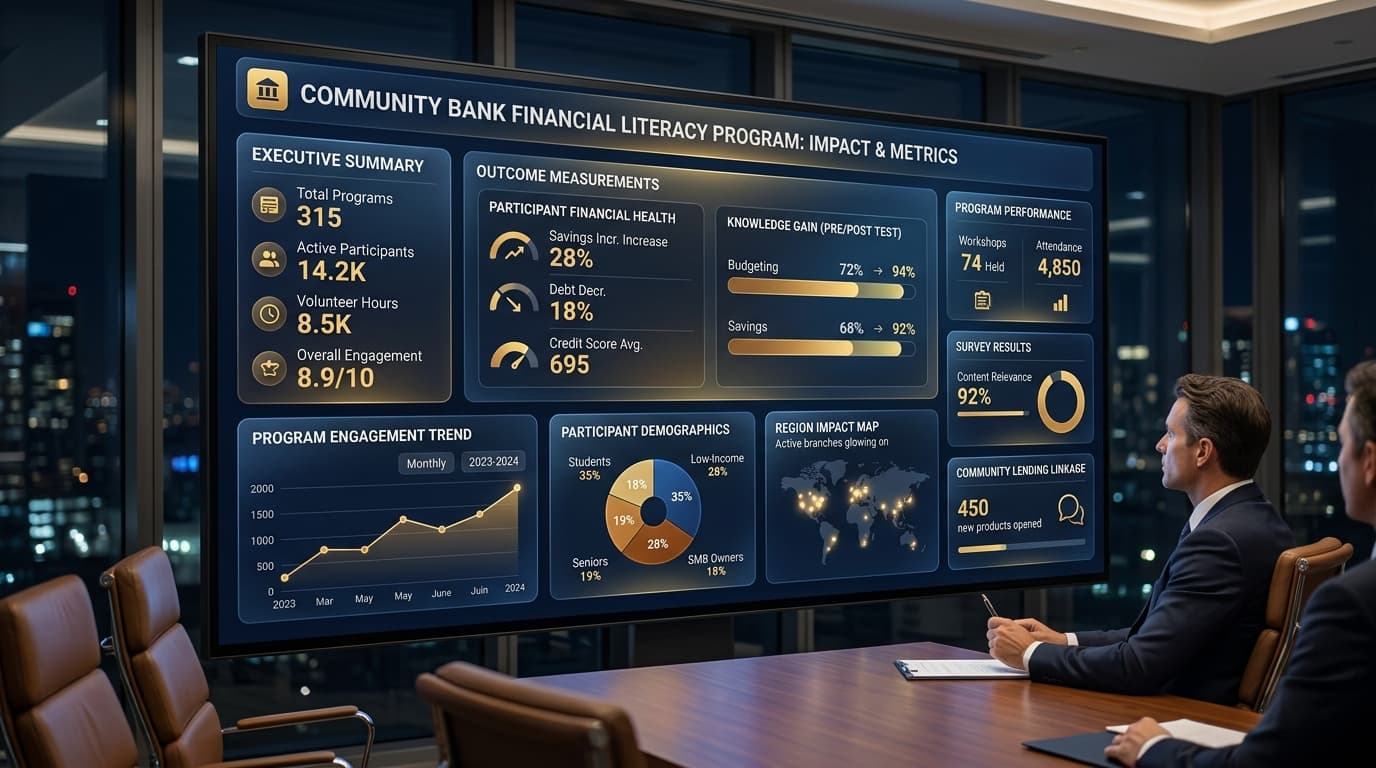
Measure financial education in three layers: what people learned, what they did differently, and what it meant for your bank and community. You don't need a research team. A few consistent habits, started on day one, will give your board and your examiners the evidence they want.

Should your bank build or buy a financial education program? Compare cost, speed, and risk, plus vendor due diligence questions.

Banks proved members want proactive AI guidance. Here's why credit unions are positioned to do it better, the guardrails, and a starting plan.

Gen Z still banks with traditional banks, but fintech is winning their new accounts. Here's why, and a playbook for community banks.

What banks actually gain from financial education: research on credit scores, delinquency, and loyalty, plus the metrics to track in a pilot.

How financial education earns CRA credit for community banks, what the 2026 OCC and FDIC proposal changes, and a checklist to stay on solid ground.

Discover the behavioral pitfalls, hidden fees, and lack of structure that cause new investors to lose capital. Learn how simulation and structured education reverse these outcomes.

Discover how multimodal cognitive learning accelerates financial literacy. Combine visual diagrams, hands-on simulation, audio debriefs, and text to master market principles.

A practical framework for high schools and districts implementing mandatory personal finance courses in 2026. Standards, simulations, and turnkey bank sponsorship.

Learn how short-term capital gains tax, state income tax, and bid-ask spreads erode investment returns. Explore how 50-state tax modeling in simulators protects real money.

Do you need to pay for financial education? Discover what free platforms provide vs when premium analytics and multi-portfolio simulations are worth the investment.

Compare the best free paper trading simulators for beginners in 2026. Discover how virtual portfolios compare across platforms.

Learn how to practice investing without risking capital. Explore paper trading, virtual market simulators, and educational tools for beginners.

Follow this graduation checklist to master key financial habits before risking real capital. The milestones every self-taught investor should hit.

A practical 7-step plan for beginners: build a cash cushion, set goals, learn account types, understand fees and risk, and practice with virtual money first.
Want to go deeper? Explore the Knowledge Vault for structured financial education.